1957 Letter
WARREN E. BUFFETT
5202 Underwood Ave. Omaha, Nebraska
SECOND ANNUAL LETTER TO LIMITED PARTNERS
The General Stock Market Picture in 1957
1957年股票市场的总体情况
In last year's letter to partners, I said the following:
在上年致合伙人的信中,我说过以下内容:
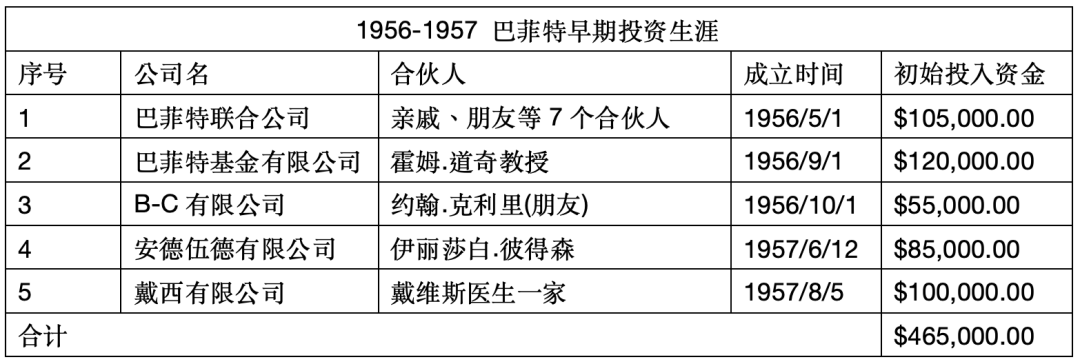
【注意这里致信的对象是有限合伙人,而不是股东。1956、1957年是巴菲特投资事业的真正起点。彼时他的老师格雷厄姆准备退休,并希望巴菲特接替自己成为公司的老板。但巴菲特选择以合伙公司的形式进行资金管理。至1957年8月,巴菲特作为普通合伙人,已先后设立了五家合伙公司。大多数合伙人是巴菲特的亲朋好友
】
My view of the general market level is that it is priced above intrinsic value. This view relates to blue-chip securities. This view, if accurate, carries with it the possibility of a substantial decline in all stock prices, both undervalued and otherwise. In any event I think the probability is very slight that current market levels will be thought of as cheap five years from now. Even a full-scale bear market, however, should not hurt the market value of our work-outs substantially.
我对整体市场水平的看法是,它的价格高于其内在价值。这个观点与蓝筹股有关。如果该观点准确的话,那么所有股票(无论是被低估的还是其他的)都将面临大幅下跌的可能。无论如何,在未来五年,我认为当前市场价格被低估的可能性都很小。不过,即使全面熊市将至,我们的套利类策略(work-out)的市场价值也不会遭受实质性损害。
【蓝筹股:Blue-Chip,术语名称来源于赌场中筹码的颜色。通常蓝色筹码代表较高的金额,引申为最大规模和最大市值的上市公司。】
If the general market were to return to an undervalued status our capital might be employed exclusively in general issues and perhaps some borrowed money would be used in this operation at that time. Conversely, if the market should go considerably higher our policy will be to reduce our general issues as profits present themselves and increase the work-out portfolio.
如果整体市场下跌到被低估的状态,我们的资本将完全用于普通股投资(general issues),甚至通过借款进行这些操作。反之,如果市场大幅上涨,我们会随着利润实现,减少持有普通股,并在组合中增加套利类策略的占比。
All of the above is not intended to imply that market analysis is foremost in my mind. Primary attention is given at all times to the detection of substantially undervalued securities.
所有以上观点,并不代表在我心中市场分析是最重要的事情。我们始终把主要精力放在寻找显著被低估的证券上。
The past year witnessed a moderate decline in stock prices. I stress the word "moderate" since casual reading of the press or conversing with those who have had only recent experience with stocks would tend to create an impression of a much greater decline. Actually, it appears to me that the decline in stock prices has been considerably less than the decline in corporate earning power under present business conditions. This means that the public is still very bullish on blue chip stocks and the general economic picture. I make no attempt to forecast either business or the stock market; the above is simply intended to dispel any notions that stocks have suffered any drastic decline or that the general market, is at a low level. I still consider the general market to be priced on the high side based on long term investment value.
上一年我们见证了股票价格的温和下跌。我强调“温和”这个词,是因为在读到相关新闻或者与那些刚刚接触股票的人交流的时候,会让人产生一种错觉股票已经跌的十分厉害。
实际上对我来说,股票价格的下跌幅度,远不如企业在当前情况下盈利能力的下滑。这意味着,公众仍然对蓝筹股和整体经济非常乐观。我不尝试预测商业或股市;以上只是为了消除任何关于股市正遭受严重下跌或市场正处于低位的看法。我仍然认为基于长期投资价值来看,市场的估值偏高。
【这里面提到了一般投资人、公众从不同出发点,对总体市场价格、企业的股票价格、企业经营情况和盈利情况等问题的思考和巴菲特本人的观点。不同出发点和预期会带来截然不同的判断。简而言之,巴老从企业经营情况出发,看到当前价格仍然偏高,后市仍有相当的下行空间。相较于主观判断大势、个股的相对位置,更加可靠】
Our Activities in 1957
我们在1957年的行动
The market decline has created greater opportunity among undervalued situations so that, generally, our portfolio is heavier in undervalued situations relative to work-outs than it was last year. Perhaps an explanation of the term "work-out" is in order. A work-out is an investment which is dependent on a specific corporate action for its profit rather than a general advance in the price of the stock as in the case of undervalued situations. Work-outs come about through: sales, mergers, liquidations, tenders, etc. In each case, the risk is that something will upset the applecart and cause the abandonment of the planned action, not that the economic picture will deteriorate and stocks decline generally. At the end of 1956, we had a ratio of about 70-30 between general issues and work-outs. Now it is about 85-15.
市场下跌已经在被低估的普通股方面创造了更大的机会,总体来说,我们去年的投资组合在低估类普通股的仓位重于套利类。或许有必要在此解释下“套利类”这个术语。它是指一项投资,依赖于特定公司行动获得利润,而不是在被低估后获得普遍的股价上涨。“套利类”,包括,出售、兼并、清算、收购要约等。风险源自某些因素可能打乱计划,导致预定行动失败,而不是经济形势恶化导致的股票普遍下跌。在1956年末,我们在普通股投资和套利类之间的比例大约是70:30,现在这个比例大概是85:15。
During the past year we have taken positions in two situations which have reached a size where we may expect to take some part in corporate decisions. One of these positions accounts for between 10% and 20% of the portfolio of the various partnerships and the other accounts for about 5%. Both of these will probably take in the neighborhood of three to five years of work but they presently appear to have potential for a high average annual rate of return with a minimum of risk. While not in the classification of work-outs, they have very little dependence on the general action of the stock market. Should the general market have a substantial rise, of course, I would expect this section of our portfolio to lag behind the action of the market.
在过去一年,我们在两只股票上建立了头寸。这些头寸的规模已经达到影响公司决策的程度。其中一个头寸占各个合伙人投资组合的10%至20%之间,另一个占大约5%。这些投资可能需要三到五年时间来完成,但目前看来,它们已显示出高回报率和较小的风险。同时,虽然它们不属于套利类投资,但它们与整体市场表现的关联性很低。当然,如果整体市场出现大幅上涨,我想这部分投资组合也会跑输市场。
Results for 1957
1957年的业绩
In 1957 the three partnerships which we formed in 1956 did substantially better than the general market. At the beginning of the year, the Dow-Jones Industrials stood at 499 and at the end of the year it was at 435 for a loss of 64 points. If one had owned the Averages, he would have received 22 points in dividends reducing the overall loss to 42 points or 8.470% for the year. This loss is roughly equivalent to what would have been achieved by investing in most investment funds and, to my knowledge, no investment fund invested in stocks showed a gain for the year.
在1957年,我们于1956年成立的三个合伙企业的表现明显优于整体市场。年初,道琼斯工业指数为499,年末降至435,损失了64点。如果一个人持有这些平均指数,他将获得22点的股息,从而将整体损失减少到42点,年损失率为8.47%。这个损失大致相当于大多数投资基金的表现,据我所知,没有任何投资基金在股票投资上实现了年度收益。
All three of the 1956 partnerships showed a gain during the year amounting to about 6.2%, 7.8% and 25% on year end 1956 net worth. Naturally a question is created as to the vastly superior performance of the last partnership, particularly in the mind of the partners of the first two. This performance emphasizes the importance of luck in the short run, particularly in regard to when funds are received. The third partnership was started the latest in 1956 when the market was at a lower level and when several securities were particularly attractive. Because of the availability of funds, large positions were taken in these issues. Whereas the two partnerships formed earlier were already substantially invested so that they could only take relatively small positions in these issues.
1956年成立的三个合伙企业在这一年中都实现了收益,分别约为上年末净资产的6.2%、7.8%和25%。一个随之而来的问题是,为什么最后一个合伙企业的表现远远优于前两个合伙企业。这个表现差异强调了在短期,“运气”的重要性,尤其是在资金到位的时机上。第三个合伙企业是在1956年市场水平较低时成立的,当时一些证券的价格特别具有吸引力。由于资金的可用性,较大的头寸用在了这些证券中。而前两个更早成立的合伙企业已经将大部分资金投资于其他标的,因此只能在这些证券中采取相对较小的头寸。
Basically, all partnerships are invested in the same securities and in approximately the same percentages. However, particularly during the initial stages, money becomes available at varying times and varying levels of the market so there is more variation in results than is likely to be the case in later years. Over the years, I will be quite satisfied with a performance that is 10% per year better than the Averages, so in respect to these three partnerships, 1957 was a successful and probably better than average, year.
基本上,所有合伙企业都以大致相同的比例投资于相同的证券。然而,在不同时间和不同市场价格投入资金,初期结果的变化会比未来几年可能出现的变化要大得多。随着时间的推移,我会对年均表现比市场平均水平高出10%的结果感到非常满意,因此就这三个合伙企业而言,1957年是一个成功的,且可能优于我们自己平均水平的一年。
【如果在投资的早期就树立一个正确的目标,那么在长期执行的过程中,就可以保持一直在正路上,不至于因为追求更高回报而参与一些会产生巨大亏损的项目中】
Two partnerships were started during the middle of 1957 and their results for the balance of the year were roughly the same as the performance of the Averages which were down about 12% for the period since inception of the 1957 partnerships. Their portfolios are now starting to approximate those of the 1956 partnerships and performance of the entire group should be much more comparable in the future.
在1957年中期成立的两个合伙企业,它们在剩余时间的业绩大致与平均水平相同,而自1957年合伙企业成立以来,平均水平下跌了约12%。它们的投资组合现在开始接近1956年合伙企业的投资组合,未来整个集团的表现应该会更加可比。
Interpretation of results
对收益的解读
To some extent our better than average performance in 1957 was due to the fact that it was a generally poor year for most stocks. Our performance, relatively, is likely to be better in a bear market than in a bull market so that deductions made from the above results should be tempered by the fact that it was the type of year when we should have done relatively well. In a year when the general market had a substantial advance I would be well satisfied to match the advance of the Averages.
我们在1957年的表现优于平均水平,在某种程度上说,部分原因是这一年大多数股票的表现普遍较差。相对而言,我们在熊市中的表现可能会优于牛市,因此从上述结果中得出的结论应考虑到这一点,即这是一个我们应该表现相对较好的年份。在整体市场有显著上涨的年份,我会对与平均水平的上涨持平感到非常满意。
【类似的表述在之后的半个多世纪,被反复提及,历久弥新。体现了巴菲特投资风格跨越周期的稳健。虽然是否适用于其他国家/地区和年代众说纷纭,但这个稳固的风格本身就已经是相当值得研究的活化石。
今年上半年(2024),有相当多的投资者批评伯克希尔又在AI狂欢盛宴中,跑输标普500。】
I can definitely say that our portfolio represents better value at the end of 1957 than it did at the end of 1956. This is due to both generally lower prices and the fact that we have had more time to acquire the more substantially undervalued securities which can only be acquired with patience. Earlier I mentioned our largest position which comprised 10% to 20% of the assets of the various partnerships. In time I plan to have this represent 20% of the assets of all partnerships but this cannot be hurried. Obviously during any acquisition period, our primary interest is to have the stock do nothing or decline rather than advance. Therefore, at any given time, a fair proportion of our portfolio may be in the sterile stage. This policy, while requiring patience, should maximize long term profits.
可以明确地说,我们的投资组合在1957年底的价值比1956年底更高。这既是由于整体价格的下降,也因为我们有更多时间去获取那些需要耐心才能获得的显著被低估的证券。我之前提到过我们最大的头寸,占各个合伙企业资产组合的10%到20%。我计划在未来将其比例提高到所有合伙企业资产的20%,但这不能急于求成。显然,在任何收购期间,我们的主要关注点是目标股票的价格保持不动或下跌,而不是上涨。因此,在任何时刻,我们的投资组合中可能会有相当一部分处于“无效”状态。虽然这种策略需要耐心,但应该能最大化长期利润。
I have tried to cover points which I felt might be of interest and disclose as much of our philosophy as may be imparted without talking of individual issues. If there are any questions concerning any phase of the operation, I would welcome hearing from you.
我试图涵盖一些我认为可能感兴趣的要点,并尽可能披露我们的投资理念,而不谈论具体的个股。如果对任何操作方面的问题有疑问,非常欢迎与我联系。
注:
虽然在1957年的致股东信的开头部分,列出这封信是SECOND ANNUAL LETTER,但暂时我能找到的最早股东信只有到1957年,后续如果能找到,再补上。
~完~
原创不易
如果您觉得本文有价值
还请点赞打赏,以资鼓励
(1元即可)