译者按:1959年美股市场逐渐出现阶段顶部的征兆。本年也是巴菲特投资桑伯恩地图公司的第二年。对于连续多年的投资,计划尽量在第一次出现于股东信时标出公司名及简要信息,并在巴菲特退出或有阶段性变化时统一编写注释。译文中的绿色字为译者注解和心得,可选择性阅读。道琼斯工业指数(1940-1980)(红框为1959年)(按通货膨胀调整,来源:https://www.macrotrends.net/1319/dow-jones-100-year-historical-chart)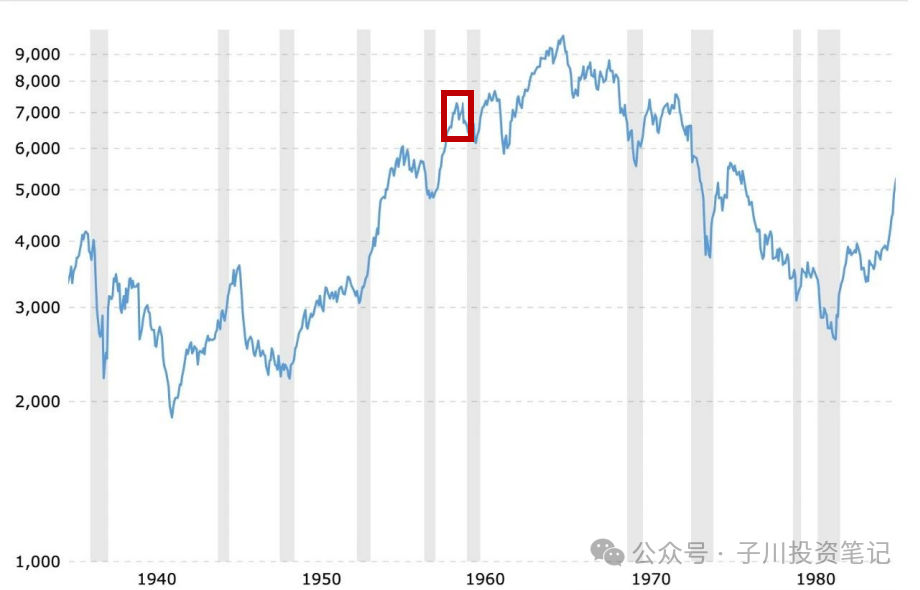
5202 Underwood Ave. Omaha, NebraskaThe General Stock Market in 1959:
1959年股市概况:
The Dow-Jones Industrial Average, undoubtedly the most widely used index of stock market behavior, presented a somewhat faulty picture in 1959. This index recorded an advance from 583 to 679, or 16.4% for the year. When the dividends which would have been received through ownership of the average are added, an overall gain of 19.9% indicated for 1959.
道琼斯工业平均指数无疑是应用最广泛的股市行为指数,却在1959年呈现出有些失真的图景。该指数从583点上涨到679点,全年录得16.4%涨幅。如果再加上持有该指数所获得的股息,全年整体收益增涨了19.9%。Despite this indication of a robust market, more stocks declined than advanced on the New York Stock Exchange during the year by a margin of 710 to 628. Both the Dow-Jones Railroad Average and Utility Average registered declines.尽管这是个市场强劲的迹象,但在纽约证券交易所,下跌股票的数量却比上涨的要多,分别是710和628支。道琼斯铁路平均指数和公共事业平均指数也均出现下跌。Most investment trusts had a difficult time in comparison with the Industrial Average. Tri-Continental Corp. the nation's largest closed-end investment company (total asset $400 million) had an overall gain of about 5.7% for the year. Fred Brown, its President, had this to say about the 1959 marked in a recent speech to the Analysts Society:"But, even though we like the portfolio, the market performance of Tri-Continental's holdings in 1959 was disappointing to us. Markets in which investor sentiment and enthusiasm play so large a part as those of 1959, are difficult for investment managers trained in values and tuned to investing for the long-term. Perhaps we haven't had our space boots adjusted properly. However, we believe that there is a limit to risks that an investing institution such as Tri-Continental should take with its stockholders' money, and we believe that the portfolio is in shape for the year ahead."和工业平均指数比起来,大多数投资信托的表现都欠佳。三大洲公司(Tri-Continental Corp.)是美国最大的封闭式投资公司(总资产4亿美元),全年整体收益约为5.7%。其总裁弗雷德·布朗(Fred Brown)在最近一次对分析师协会的演讲中表示:“尽管我们喜欢我们的投资组合,但三大洲在1959年的市场表现令人感到失望。像1959年这样以投资者情绪和热情主导的市场,对那些受过价值投资训练并专注于长期投资的投资经理来说很困难。也许我们没有为适应这样的情况调整好我们的太空靴。但我们相信,像三大洲这样的投资机构在使用股东资金时只应该承担有限风险,而且我们也相信我们的投资组合为下一年做好了准备。”Massachusetts Investors Trust, the country's largest mutual fund with assets of $1.5 billion showed an overall gain of about 9% for the year.马萨诸塞投资信托(Massachusetts InvestorsTrust),作为拥有15亿美元资产的美国最大共同基金,全年整体收益约为9%。Most of you know I have been very apprehensive about general stock market levels for several years. To date, this caution has been unnecessary. By previous standards, the present level of "blue chip" security prices contains a substantial speculative component with a corresponding risk of loss. Perhaps other standards of valuation are evolving which will permanently replace the old standard. I don't think so. I may very well be wrong; however, I would rather sustain the penalties resulting from over-conservatism than face the consequences of error, perhaps with permanent capital loss, resulting from the adoption of a "New Era" philosophy where trees really do grow to the sky.你们中的大多数人都知道,我已经连续多年对股市的整体水平感到非常担忧。迄今为止,这种谨慎都没什么必要。根据以往标准,当前“蓝筹”证券的价格水平包含了相当大投机成分,并伴有相应损失风险。也许其他估值标准正在逐步演化,并将永久取代旧标准。但我并不这么认为。虽然我很可能是错的;然而,我宁愿承受过于保守导致的惩罚,也不愿面对可能导致永久性资本损失的错误。这种错误源于采用了“新纪元”哲学,认为大树真的会长到天上去。【译者注:在市场周期性变化中,人们总是默默的调整对增长率大小的估计和增长率能延续多久的估计,并且假装这个估值方法似乎天然应该如此。】There has been emphasis in previous letters on a suggested standard of performance involving relatively good results (compared to the general market indices and leading investment trusts) in periods of declining or level prices but relatively unimpressive results in rapidly rising markets.在之前的股东信中,我们多次强调了对评判“业绩表现”的建议标准,我们的投资通常在市场整体下跌或持平期间,比一般市场指数和领先的投资信托表现更好;但在市场快速上涨期间则表现相对不佳。We were fortunate to achieve reasonably good results in 1959. The six partnerships that operated throughout the year achieved overall net gains ranging from 22.3% to 30.0%, and averaging about 25.9%. Portfolios of these partnerships are now about 80% comparable, but there is some difference due to securities and cash becoming available at varying times, payments made to partners, etc. Over the past few years, there hasn't been any partnership which has consistently been at the top or bottom of performance from year to year, and the variance is narrowing as the portfolios tend to become comparable.幸运的是,我们在1959年取得了相对良好的业绩。全年运营的六个合伙企业实现了22.3%到30.0%不等的整体净收益,平均约为25.9%。现在这些合伙企业的投资组合中大约有80%是可比的,但由于每家企业的证券和现金的可动用时点不同,以及支付给合伙人款项等原因,合伙企业间的回报率仍存在一些差异。在过去几年中,没有任何一个合伙企业的表现始终最好或最差。随着投资组合趋于可比,合伙企业间的差异也正在缩小。The overall net gain is determined on the basis of market values at the beginning and end of the year adjusted for payments made to partners or contributions received from them. It is not based on actual realized profits during the year, but is intended to measure the change in liquidating value for the year. It is before interest allowed to partners (where that is specified in the partnership agreement) and before any division of profit to the general partner, but after operating expenses.整体净收益是基于年初和年末的市场价值决定,并依据支付给合伙人的款项或收到合伙人付款作出调整。这个收益不是基于年度内实际实现利润,而是旨在衡量年度内清算价值的变化。它尚未扣除应付给合伙人的利息(如果合伙协议中有规定的话),也尚未将任何利润分配给普通合伙人,但是已经扣除了运营费用。【译者注:本段简记,整体净收益:+净收益+收到合伙人款项-支付合伙人款项-(待减未减的应付利息)-运营费用】The principal operating expense is the Nebraska Intangibles Tax which amounts to .4% of market value on practically all securities. Last year represented the first time that this tax had been effectively enforced and, of course penalized our results to the extent of .4%.主要运营费用是内布拉斯加州征收的无形资产税,这项税几乎对所有证券按其市场价值的0.4%征收。该税种在去年首次执行,当然也使我们的业绩表现降低了0.4%。当前投资组合:
Last year, I mentioned a new commitment which involved about 25% of assets of the various partnerships. Presently this investment is about 35% of assets. This is an unusually large percentage, but has been made for strong reasons. In effect, this company is partially an investment trust owing some thirty or forty other securities of high quality. Our investment was made and is carried at a substantial discount from asset value based on market value of their securities and a conservative appraisal of the operating business.去年,我提到了一项新的投资承诺,约涉及各合伙企业资产的25%。目前这项投资约占全部合伙企业资产的35%。这个比例异常之大,但我们有充分的理由进行这项投资。实际上,这家公司有一部分是一个投资信托,拥有三四十种高质量证券。我们的投资决策和账面价值计算,既基于按市场价值对这部分证券资产进行较大折扣后的评估,也基于对该公司主营业务的保守评估。【译者注:上面提到的公司是桑伯恩地图公司(Sanborn stock)。其主营业务是供保险公司使用的地图服务。同时该司也持有一部分证券资产组合。巴菲特于1957年发现该家公司,在1958、1959年以合伙企业和其个人名义连续增持;并发动朋友圈子,甚至说服他父亲经纪公司里的客户购买,最终获得到对该企业的控制权。1960年,该项投资完成退出,获利50%。关于对巴菲特投资桑伯恩地图公司过程的完整注解,我将放在巴菲特完成处置该项投资之后的那一年股东信中。】We are the company’s largest stockholder by a considerable margin, and the two other large holders agree with our ideas. The probability is extremely high that the performance of this investment will be superior to that of the general market until its disposition, and I am hopeful that this will take place this year.我们以显著优势成为该公司的最大股东,并且另外两位大股东也同意我们的理念。该投资直到其出售为止,表现都极有可能优于整体市场,我也希望在今年内能够出售。【译者注:短短两句话,体现出了巴菲特投资理念的杀伐决断。决意投资之后就要拿到目标企业的绝对控制权,并能够完全按其意愿对目标企业的经营、资产配置、投融资和股东权益方面进行改变。这与后来给人的不参与经营,完全相信被投企业的刻板印象大相径庭。另外,这些一两年就退出的投资项目,展示了巴菲特在决意退出时也绝不拖泥带水。在他早期的投资中,不乏一些与被投资企业的股东、管理层、员工或当地社区的不愉快经历。但纵然如此,合伙企业也基本做到获得满意回报和全身而退。以上,令人感受到巴菲特对,时长、时点、价格、价值、风险、回报的精准把握。非常难得。】The remaining 65% of the portfolio is in securities which I consider undervalued and work-out operations. To the extent possible, I continue to attempt to invest in situations at least partially insulated from the behavior of the general market.投资组合中的剩余65%主要是我认为被低估的证券和套利类交易。在可能的情况下,我将继续尝试投资那些至少部分与整体市场表现相隔离的标的。This policy should lead to superior results in bear markets and average performance in bull markets. The first prediction may be subject to test this year since, at this writing, the Dow-Jones Industrials have retraced over half of their 1959 advance.这一策略应该在熊市中带来更优的业绩,而在牛市中表现一般。关于在熊市中表现的预测可能在今年就会得到验证,因为在我写下这篇文章时,道琼斯工业平均指数已经回撤了1959年涨幅的一半。Should you have any questions or if I have not been clear in any respect, I would be very happy to hear from you.如果您有任何问题,或者我在任何方面没有表达清楚,我非常乐意听取您的意见。~完~
原创不易
如果您觉得本文有价值
还请点赞打赏,以资鼓励
(1元即可)
~End~
